
Orbital AI Compute After Google's 100x Warning: A Practical Checklist for Capacity Planners | AIdataNewsGlobal
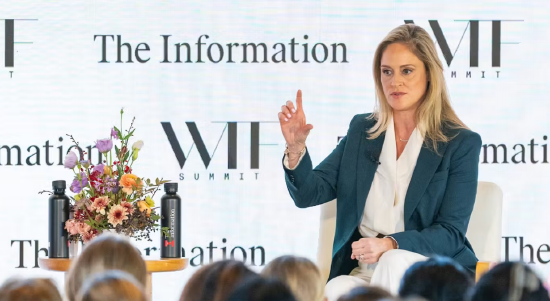
Space-based data centres have stopped being an engineering story and become a valuation story — and that shift is exactly what makes them dangerous to plan around. A technology can be genuinely promising and still be worthless inside a five-year compute budget. On the WTF Summit stage this week, the executive responsible for energy strategy across Google's data centres, Amanda Peterson Corio, attached a hard number to that gap: orbital builds could cost up to 100 times as much as terrestrial ones. Then she explained why the company keeps experimental hardware in orbit anyway. Read as a working document rather than a verdict, her remarks offer a template for how any organisation should discount frontier claims before they leak into a procurement model.
Five facts busy readers should take away
- Cost gap: Peterson Corio described putting compute hardware into orbit as "extremely expensive — up to 100 times the cost of building on the ground", with launch as the dominant term.
- Break-even condition: a paper published last autumn by Google researchers together with company chief researcher James Manyika argued that orbital power-normalised compute becomes cost-competitive only once launch falls to $200 per kilogram or less — a threshold the team expects to be reachable around 2035, contingent on Starship development progress and rising launch cadence.
- Third-party yardsticks: a June 2026 Barclays note put orbital capacity at roughly $50 million per megawatt, and Wood Mackenzie modelled a hypothetical 1 GW orbital facility at about US$170 billion, with launch and satellites alone accounting for roughly 60% of that bill.
- Constraint on the ground: in Peterson Corio's reading the blocker is "approvals, not electrons" — interconnection review and impact studies, not a shortage of generation.
- Timetable dispute: Elon Musk says SpaceX could build a space data centre as early as next year; Jeff Bezos expects 1-gigawatt orbital facilities within ten years; OpenAI CEO Sam Altman calls the idea "highly unrealistic" today.
What the world's largest data-centre operator actually said
Peterson Corio's argument had two halves. The first was arithmetic: the price of lifting compute hardware into orbit dwarfs everything else in the bill of materials, which is why she landed on 100 times as the worst-case multiple against a ground build. The second was operational. On the ground, a data-centre team can swap a failed server, reroute a fibre, or re-commission a cooling loop the same afternoon; in orbit, none of that is possible, and every upgrade becomes a new launch rather than a maintenance window.
Her second theme was reputational. She argued that part of the rising backlash against terrestrial data centres in the US is attributable to young entrants that should be held to a higher standard of scrutiny. Enterprises that had worked in data-centre construction for a long time before the current AI compute boom, she noted, "done things quite properly", and their projects rarely provoked controversy. She did not name companies, but the context is not subtle: in recent years a wave of novice developers entered the AI data-centre market, and even established names such as Oracle have faced local residents' opposition to their projects.
Three independent cost yardsticks — and the gap that still has to close
Google is not the only institution that has tried to price the idea. Comparing its own modelling with two sell-side and consultancy estimates is the fastest way for a planning team to see how wide the uncertainty band is.
| Assessment | Headline figure | Condition or comparison | When published |
|---|---|---|---|
| Google research team paper (with James Manyika) | Parity only if launch is $200 per kilogram or less | Orbital compute per unit of power roughly matches terrestrial levels; achievable around 2035 depending on Starship and launch cadence | Last autumn |
| Google's own operational view (Peterson Corio, WTF Summit) | Up to 100 times terrestrial build cost at the extreme | Launch cost is described as "extremely expensive"; maintenance and upgrade are unsolved | This week |
| Barclays (analyst Brendan Lynch, note "Ashburn, then Abilene, then space") | About $50 million per megawatt orbital, roughly three times ground | Five-year full-cycle cost of about $51 billion per GW against about $16 billion per GW on the ground; flagged launch, radiation-hardened hardware, heat rejection, bandwidth and regulation as five barriers | June 2026 |
| Wood Mackenzie orbital data-centre report | About US$170 billion for a hypothetical 1 GW orbital facility | More than three times an equivalent terrestrial site; launch plus satellites are around 60% of the cost. Demand context: global data-centre power demand of 460 TWh in 2026, forecast to reach 1,280 TWh by 2030 and 3,700 TWh by 2040 | June 2026 |
The arithmetic is sobering. Research from Cambridge's Judge Business School reported that the average price of sending a kilogram of payload to low Earth orbit was about $3,868 in 2025 and projected a fall of more than 58% to roughly $1,569 as reuse scales, with steeper declines only late in the projection window. That still leaves today's market an order of magnitude above Google's own break-even condition of $200 per kilogram or less — which is why the "around 2035" date, not the "as early as next year" date, is the number worth putting in a planning model.
A six-step test for any orbital compute claim
- Ask what launch price the claim assumes. Google's threshold is $200 per kilogram or less; if a vendor's deck does not state a per-kilogram assumption, the claim is unpriced. Reconcile it against published market prices rather than internal marginal costs.
- Ask how heat leaves the chip. There is no convection in vacuum, so capacity is bounded by radiator area and mass, not by the power budget of the solar array. Google's own prototype testing has reportedly been constrained by short duty cycles while radiators shed heat.
- Ask what happens when a component fails. Any roadmap without a serviceability answer is really a roadmap for disposable hardware, which resets depreciation to launch cadence.
- Ask about bandwidth and data residency. Downlink capacity and jurisdictional questions appear in every analyst critique, including the Barclays list of five barriers; inference at the edge may tolerate them, model training will not.
- Ask about the licence. Spectrum rights, debris and re-entry planning, and orbital-permit uncertainty remain open in most jurisdictions; treat regulatory clarity as a cost line, not a footnote.
- Discount orbital savings against your own horizon. If your capacity plan ends in 2030, orbital cost curves are informational, not decision-relevant. Peterson Corio's framing of the technology as "nowhere near imminent" is the conservative default.
Google is flying hardware anyway — and that is the instructive part
The apparent contradiction is the reason this story deserves a place on a general business feed rather than a space-industry one. Despite the scepticism, Google's research team announced this month that it will work with satellite imaging company PlanetLabs to explore the feasibility of large orbital data-centre clusters. Under the project named Suncatcher, Google has already sent a small space server prototype into orbit carrying a TPU, an AI tensor processing unit co-developed with Broadcom.
Subsequent reporting on that mission fills in the practical picture: the prototype carries roughly four TPUs and on the order of a kilowatt of generated power, and Google described receiving its first in-orbit AI inference response at the end of October — a demonstration of the shortest possible link (power on, one inference, one downlink), not of sustained throughput. The next milestone Google has described is a two-satellite test of laser inter-satellite links in 2027. Sundar Pichai has characterised Suncatcher as a stepping stone toward orbital data centres rather than a product launch, and the peer-reviewed version of the project's white paper explicitly does not assess economics.
Why bother, then? Peterson Corio did not dismiss the concept, calling the direction "very interesting", and explained that Google keeps funding high-risk frontier work because the company is in the habit of "thinking about what happens 10, 20 or 30 years from now". The discipline for outside readers is to mirror that split: fund the research, but do not fund the balance sheet on the assumption that orbital capacity arrives inside the current planning cycle.
Optimists, sceptics and a $1.8 trillion narrative
The commercial stakes are why the debate has become so loud. SpaceX's orbital data-centre plan remains one of the key logics supporting its market capitalisation of roughly $1.8 trillion, and Musk has said the company could build a space data centre as early as next year. Bezos — the head of Blue Origin, Amazon founder and a SpaceX competitor — has forecast 1-gigawatt-class orbital data centres within ten years. Separate reports have suggested that Google and SpaceX have discussed cooperation on in-orbit data centres.
Altman's position is closer to Peterson Corio's than to Musk's. Beyond saying the idea is "highly unrealistic" under current conditions, he has publicly questioned the aggressive timelines. Note also the hedge in Google's own language: Peterson Corio supports the research but insists deployment is "nowhere near imminent". Between the two extremes sits the industry-wide observation that orbital builds may end up as a complement to terrestrial capacity rather than a substitute for it.
The constraint that binds this year: interconnection queues, not generation
Peterson Corio pushed back directly on the claim that US power supply cannot support AI compute growth: "Is there enough power? Of course it is." In her account the true bottleneck is the approval process required to connect to the grid, plus the long evaluation studies that precede it. Alphabet's X lab has launched a project called Tapestry and is working with PJM, the largest grid operator on the US East Coast, to use AI to accelerate those evaluations.
Regulatory friction is visible in the numbers. In Texas, state electricity regulators have already slowed approval of some data-centre projects and tightened oversight, to prevent new compute facilities from straining the grid and pushing up retail prices. Reporting on the state's reform shows how fast that terrain is moving: Senate Bill 6, enacted in 2025, forced a rework of large-load interconnection rules; the Public Utility Commission of Texas approved ERCOT's "Batch Zero" study process on June 18, 2026; a proposed non-refundable interconnection fee of $50,000 per megawatt of contracted peak demand was later softened when the final rule was adopted; and in August 2026 the governor ordered an audit and a temporary pause on certain data-centre interconnection approvals. Trade-press compilations of operator filings have also described large-load waits in PJM stretching beyond eight years in some cases, with ERCOT's large-load queue swelling to roughly 226 GW.
Meanwhile the grid's utilisation picture is better than the headlines suggest. Brian Janous, co-founder of data-centre land and power services provider Cloverleaf Infrastructure, said in an interview recently that about 45% of grid capacity sits idle for long stretches because networks are built to meet peak demand; during most of the day, he argued, there is spare capacity that data centres could absorb. On power usage effectiveness (PUE), Google has an advantage over its cloud peers: the metric measures how efficiently a facility converts electricity into compute. Google's own published data centre figures report a fleet-wide average PUE of 1.09, against an industry average in the mid-1.5 range in Uptime Institute's Global Data Center Survey series — a practical lever worth pricing before anyone proposes launching a radiator.
What Google wants the industry to standardise
Peterson Corio attributed the anti-data-centre wave in the US to "a large number of new entrants that lack the industry depth and maturity when it comes to securing land and building compute projects", again without naming firms, and said she supports binding rules and higher standards for the sector. She offered no specific regulation, but pointed to commitments Google is already making: deeper investment in host communities and pre-positioned plans so that a stalled project does not leave locals "forced to pay the bill".
Central to that is a pledge to keep covering grid upgrade costs for 15 to 20 years, so that a community is not left holding infrastructure debt if a project never materialises. This model of pre-committing to grid infrastructure costs has now landed in nine or more US states and, in her words, is "expanding extremely fast". Her accompanying standards list:
- Google pays electricity bills and property taxes in full;
- it posts bonds to fund land restoration if a project is abandoned;
- it drops confidentiality agreements signed with local governments.
The backdrop is investors re-rating a cohort of emerging AI cloud vendors — many backed by heavy Nvidia investment — that have borrowed aggressively and commissioned data centres at speed without long operating records. The companies Peterson Corio suggested need tighter standards probably include those vendors. Google also disclosed that a growing share of its compute demand will rely on third-party capacity, without naming partners; SpaceX is one possibility. The stated reason is simple: self-built data centres are not being delivered as fast as demand is growing.
Common pitfalls for teams writing compute plans
- Treating energy scarcity as the binding constraint. Interconnection review, transformer lead times and local permitting decide delivery dates far more often than generation capacity.
- Copying an aggressive launch date into a depreciation schedule. Reconcile with the break-even cost test first; the credible range in public analysis spans about $200 per kilogram or less on the optimistic end and multiples of current market pricing today.
- Assuming orbit removes community opposition. It removes neighbours, not obligations: spectrum, debris, licensing and disclosure still have owners.
- Ignoring efficiency on the ground. A PUE gap of the order of 1.09 versus the mid-1.5 industry average is a larger, faster, cheaper saving than any announced orbital pilot.
- Skipping counterparty scrutiny on new developers. Google's own list of standards — taxes, bonds, no secrecy agreements, long-dated grid-cost commitments — is a usable due-diligence checklist for any landlord or neocloud partner.
FAQ: the questions planners ask first
Is the US really short of electricity for AI data centres?
Not according to Peterson Corio: "Is there enough power? Of course it is." Her view is that permitting, grid connection studies and interconnection queues are the bottleneck. Janous's figure of about 45% of capacity idling to reserve peak headroom supports the same reading, though Texas's regulatory slowdown shows the friction is real.
What price has to fall for orbital compute to make sense?
Launch. Google's research, published last autumn with James Manyika among the co-authors, puts the crossover at $200 per kilogram or less, achievable around 2035 given Starship progress and higher launch frequency. Current published pricing remains roughly an order of magnitude higher.
Is Google's position a contradiction?
Only if you conflate research horizons with deployment horizons. The company calls the direction "very interesting", says it plans "10, 20 or 30 years" ahead, and simultaneously warns deployment is "nowhere near imminent". Suncatcher exists to test hardware survival, not to serve customers.
Whose timeline should a business case use?
The slowest credible one. Musk says as early as next year, Bezos says within ten years for 1-gigawatt facilities, Altman says the concept is highly unrealistic now, and Barclays concluded orbital builds do not threaten conventional operators within ten years. Plan for terrestrial capacity and treat orbital as optional upside.
What should we do this quarter instead?
Move early on interconnection applications, contract grid-cost commitments in advance of local approval, benchmark your provider's PUE against published averages, and reserve a share of demand for third-party capacity — the same lever Google says it now needs as self-builds lag demand.
What to watch over the next twelve months
- Any disclosed Starship flight-rate improvement that moves per-kilogram pricing toward the $200 threshold.
- Google and PlanetLabs data from the Suncatcher prototype, especially thermal duty cycles and radiation-driven memory error rates, plus the planned 2027 two-satellite laser-link test.
- Grid-operator reform in PJM and ERCOT, including AI-assisted evaluation work under the Tapestry project with Alphabet's X lab.
- Adoption of Google's community-protection template beyond the current nine or more states.
- Whether investors keep funding new-entrant AI cloud vendors whose standards Google says should be raised — and whether Nvidia-backed balance sheets can absorb delay risk.
The useful conclusion is procedural rather than prophetic. Orbital compute is a research programme with a real cost cliff, and the same week its sponsor publicly priced that cliff at up to 100 times was the week it put another TPU in orbit to learn more about it. Buyers who separate the two — funding curiosity on a 10, 20 or 30 year clock while defending a five-year capacity plan on grid queues, PUE and permitting — will neither miss the technology nor be misled by the narrative. For follow-up data or corrections, write to the AI & Data News editorial team.
Written by David Nakamura · Published by AI & Data News · Contact: editorial@aidatanews.com · More coverage at https://aidatanewsglobal.com